Most investors think maximising mutual fund returns is about finding the one fund that will outperform everything else. It rarely works that way. The investors who actually build wealth through mutual funds usually aren't the ones chasing last year's top performer, they're the ones who get a handful of basics right and stay consistent with them for years. Cost, timing, allocation, and patience matter far more than picking a "hot" fund. Here are eight strategies that genuinely move the needle, in the order they matter most.
Need Help? Request a Free Call from an Expert
Let our Experts guide you through your Investment journey. From Monthly SIP in any Fund to your Financial Planning.

Start Early and Let Compounding Do the Heavy Lifting
There is no strategy on this list that beats the advantage of time. An investor who starts saving ₹5,000 per month at the age of 25 will accumulate a significantly larger corpus than someone who begins saving ₹10,000 per month at age 35, because the effects of compounding take years to manifest.
You start earning returns on the profits you have already made. It is this 'snowball effect' that allows a small monthly contribution to grow into a substantial sum over 15 or 20 years. If you are reading this and haven't started yet, just remember one thing: the best time to start was years ago, but the second-best time is this very month.
Use SIP (Systematic Investment Plan) for Rupee Cost Averaging on Regular Investments
With a SIP (Systematic Investment Plan), you invest a fixed amount regularly instead of putting in a lump sum at once. This helps spread your investment across different market conditions and reduces the impact of short-term market fluctuations.
-
When the market falls, you can purchase more units for your fixed monthly amount.
-
When it rises, it buys fewer
-
Over time, this averages out your purchase cost, which is especially useful if you're investing out of your regular income rather than a one-time corpus
Invest Consistently, Grow Wealth, and Secure Your Future with Ease.

Match Fund Selection to Your Risk Appetite and Financial Goal
This is where many investors make a mistake, and usually, the reason is not a lack of information but haste. An individual might see a fund that delivered a 40% return over the past year and invest in it without checking whether the fund's risk profile suits them or aligns with their investment goals.
A quick way to think about it:
-
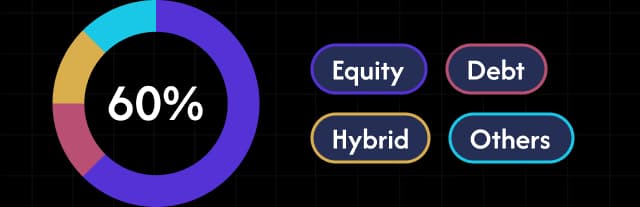
Higher risk-taking capacity and a long time horizon: Equity funds are the right choice.
-
If you are looking for stability along with decent growth, hybrid or balanced funds are better options.
-
Capital preservation is more important than aggressive growth; debt funds are a prudent choice.
Whichever category you land in, tie the investment to an actual goal, a child's education, a retirement corpus, a house down payment, rather than investing simply because a fund is trending. A fund that delivered exceptional returns last year can just as easily underperform next year, and if it doesn't match your goal or risk comfort in the first place, chasing its performance usually backfires.
Invest across different fund categories and asset classes.
Large cap, mid cap, small cap, debt, and hybrid funds don't move in sync with each other. When one category is having a weak year, another is often holding steady or gaining. Spreading your investments across a few categories rather than concentrating everything in one reduces the impact of any single category's bad year on your overall portfolio.
This does not mean you need to have five or six funds in your portfolio just to feel diversified. Beyond a certain point, it only leads to overlap, making it difficult to track what you actually hold. A large cap fund for stability, a mid cap fund for growth, and a debt fund to soften the bumps is usually enough for most investors, and the exact mix should come down to what your goals actually need, not how many funds sound impressive.
Watch the Expense Ratio and Exit Load
This is the one strategy most investors skip entirely, and it's quietly one of the most important.
The expense ratio is what the fund house deducts each year to cover fund management and operating costs, and it comes out of your investment whether the fund has a great year or a disappointing one. On paper, the gap between a fund charging 1% and one charging 2% looks trivial. Stretch that same gap across a 15 or 20 year SIP, though, and it quietly shaves off a chunk of your final corpus, money that would otherwise have kept compounding on your side.
An exit load works differently; it is a charge applied when you withdraw your money before a specified period (usually one year). While this does not negatively affect your investment, it is important to be aware of it before investing so you do not face an unexpected deduction if you need the funds on short notice.
Before finalizing any fund, it's worth spending two minutes checking both numbers in the scheme document rather than assuming they don't matter.
Review and Rebalance Your Portfolio Periodically
A portfolio you set up three years ago and haven't looked at since has probably drifted from its original allocation. If equity markets have had a strong run, your equity allocation might now be far higher than you intended, which quietly increases your risk exposure without you noticing.
Doing this twice a year is a good routine; you should certainly do it at least once. There is no need to get overly anxious about market fluctuations in the interim or to make changes to your funds every few weeks. It is easy to check this: has your money drifted away from the goals and comfort levels you started with? And if so, is it time to get things back on track? More than picking any smart fund, this single habit distinguishes investors who stay on the right path from those who have a bad experience during market downturns.
Use STP for Lump Sum Investments to Reduce Timing Risk
If you've come into a lump sum, a bonus, maturity proceeds, an inheritance, putting it all into equity funds on a single day carries real timing risk. Nobody knows whether that day falls near a market peak.
A Systematic Transfer Plan (STP ) solves this cleanly:
1. Park the lump sum in a short-term debt fund first
2. Transfer a fixed amount into your chosen equity fund every month, similar to how an SIP works
3. This spreads your entry across several months instead of one, cutting down the risk of investing everything right before a downturn
Our STP calculator can help you plan how much to transfer and for how long, according to your convenience.
Plan Tax-Efficient Exits
How and when you withdraw money is just as important as how you invest. Long-Term Capital Gains (LTCG) rules apply to equity mutual funds held for more than a year. Currently, gains exceeding ₹1.25 lakh in a financial year are taxed at 12.5%. This rate is significantly lower than the short-term tax rate applicable to units sold within one year. Planning your withdrawals around this holding period, rather than exiting impulsively, can noticeably improve your post-tax returns.
If tax saving alongside growth is part of your goal, ELSS funds are worth a look too, they come with a Section 80C deduction and a mandatory three-year lock-in, the shortest among all 80C options, which also nudges you toward the kind of long-term holding that tends to work in your favor anyway.
Conclusion
None of these eight strategies are complicated on their own. What makes the difference is doing several of them together, consistently, over years rather than months.
-
Start early
-
Invest through SIP
-
Pick funds that actually match your goals and risk appetite
-
Keep an eye on costs
-
Diversify sensibly
-
Review periodically
-
Be thoughtful about how and when you exit
That combination, not a single lucky fund pick, is what tends to separate investors who reach their goals from those who don't.
If you're ready to put any of this into practice, you can Start a SIP online in a few minutes, or explore our range of Mutual Funds to find ones that fit your goals.